Skip to content

PACE financing is repaid through your property tax bill and secured by a lien equal in rank to county taxes, while a home equity loan or HELOC is borrowed from a lender, uses your home as collateral and is repaid to that lender. That one difference shapes everything else.
It changes who qualifies, how your payments work, and what happens when you sell or refinance. This comparison walks through each point for Florida homeowners planning projects such as impact windows, impact doors or a new roof.
PACE vs Home Equity Loan vs HELOC: Side-by-Side
The table below compares the three options on the points Florida homeowners ask about most. PACE rules come from Florida law and the federal PACE rule; home equity rules come from the Consumer Financial Protection Bureau (CFPB).
| Point | PACE (Florida) | Home equity loan | HELOC |
|---|---|---|---|
| Secured by | A lien on the property, equal in rank to county taxes | Your home as collateral | Your home as collateral |
| How you pay | With your property taxes | Equal payments to your lender | Payments to your lender that can change |
| Rate and disclosure | Interest and estimated APR disclosed before signing | Fixed | Typically variable; APR disclosed |
| What it can pay for | Only qualifying improvements listed in state law | Not tied to a project list | Not tied to a project list |
| Longest term | Useful life of the improvements, 20 years at most | Set by the loan | Draw period, then repayment often over 10 or 15 years |
| Main approval checks | Taxes and mortgage current, income test, ability to repay | Your equity and the lender’s review | Your equity and the lender’s review |
| Cancel after signing | 3 business days | 3 business days | 3 days after the account opens |
| When you sell | A lender may require full payoff | Repayment often required | Generally paid off in full |
For cash, personal loans and state programs, see our guide to every home improvement financing option.
Financing may be available for qualified homeowners through independent third-party providers. Terms, eligibility and availability depend on the program and location. You can ask about financing options for your impact window project at your estimate.
How Each Option Is Secured Against Your Home
A Florida PACE assessment is a lien on the property itself, not a loan in your name from a bank. Under section 163.081, Florida Statutes, the recorded assessment is a lien “of equal dignity to county taxes and assessments,” and it is collected with your property taxes.
The same law sets two limits. The PACE lien cannot be enforced in a way that speeds up the unpaid balance, and a mortgage clause that lets your lender call the mortgage due only because you took PACE financing is unenforceable.
A home equity loan and a HELOC both borrow against your equity, which the CFPB’s HELOC booklet defines as “the value of your home minus the amount you owe on your mortgage.” The CFPB groups the home equity loan with second mortgages, and both options use your home as collateral.
Missed payments are serious with all three. The CFPB warns that if you fall behind on a HELOC, you could lose your home. Florida’s required PACE disclosure warns that unpaid assessments can lead to a tax certificate that could result in losing the property.
How You Repay: Property Tax Bill vs Loan Payments
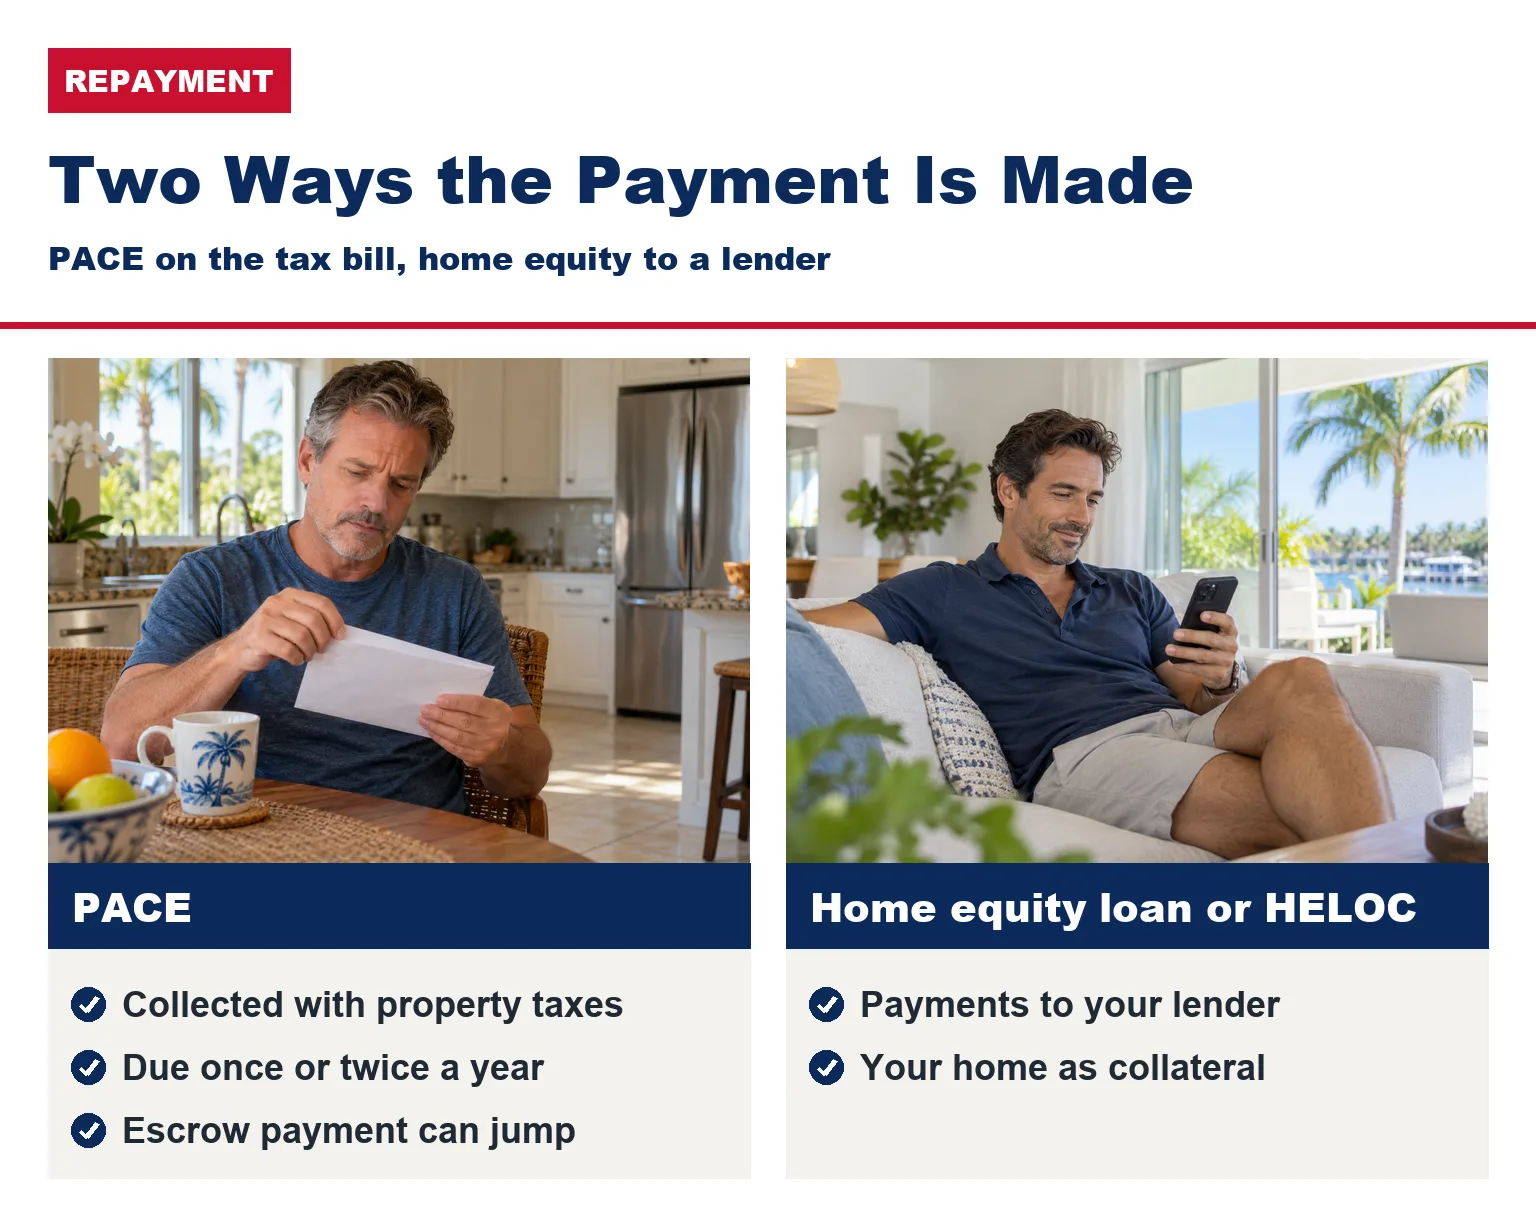
PACE payments are added to your property tax bill as a non-ad valorem assessment. The CFPB notes these payments are generally due once or twice a year, and if your taxes are paid through a mortgage escrow account, your escrow payment can jump suddenly once the assessment is added.
Florida law also shapes the PACE schedule. It allows no balloon payment and no negative amortization, and you may repay early with no penalty beyond nominal administrative costs. The term cannot run past the weighted average useful life of the improvements, and never past 20 years.
A home equity loan works like a standard installment loan. The CFPB describes it as a fixed-rate loan with equal payments that pay off the entire loan. If you need more money later, you apply for a new loan.
A HELOC has two phases. In the draw period you borrow as needed, and some plans allow interest-only payments. In the repayment period you pay back the balance, often over 10 or 15 years, or in some plans all at once as a balloon payment.
Because HELOC rates are typically variable, your payment can change even if you do not borrow more. To weigh the cost of a PACE offer, read what sets Florida PACE interest rates and fees.
Who Qualifies for PACE vs a Home Equity Loan or HELOC
PACE approval in Florida starts with the property’s records, and it now looks at your income too. Under section 163.081, three of the main tests are:
- Your county or city has an authorized PACE program, and your taxes and mortgage are current.
- The total PACE assessment stays within 20 percent of the home’s just value, unless your mortgage holders agree in writing.
- Estimated yearly payments on all PACE agreements on the home stay within 10 percent of household income, verified with evidence.
Florida’s full list of checks, including liens, bankruptcy and reverse mortgages, is in our guide to how PACE financing works in Florida.
A federal rule adds another check. The CFPB’s residential PACE financing rule treats PACE as credit under the Truth in Lending Act and requires a good-faith determination of your ability to repay, verified with reliable third-party records.
So the old idea that PACE ignores your finances no longer holds. Florida’s income test looks at what you earn, and the federal repayment check also weighs what you already owe.
A home equity loan or HELOC is approved on the lender’s own terms. According to the CFPB, you can generally borrow a percentage of your home’s appraised value minus what you owe on your mortgage, and the lender reviews your finances before it approves the loan.
What Each Option Can Pay For
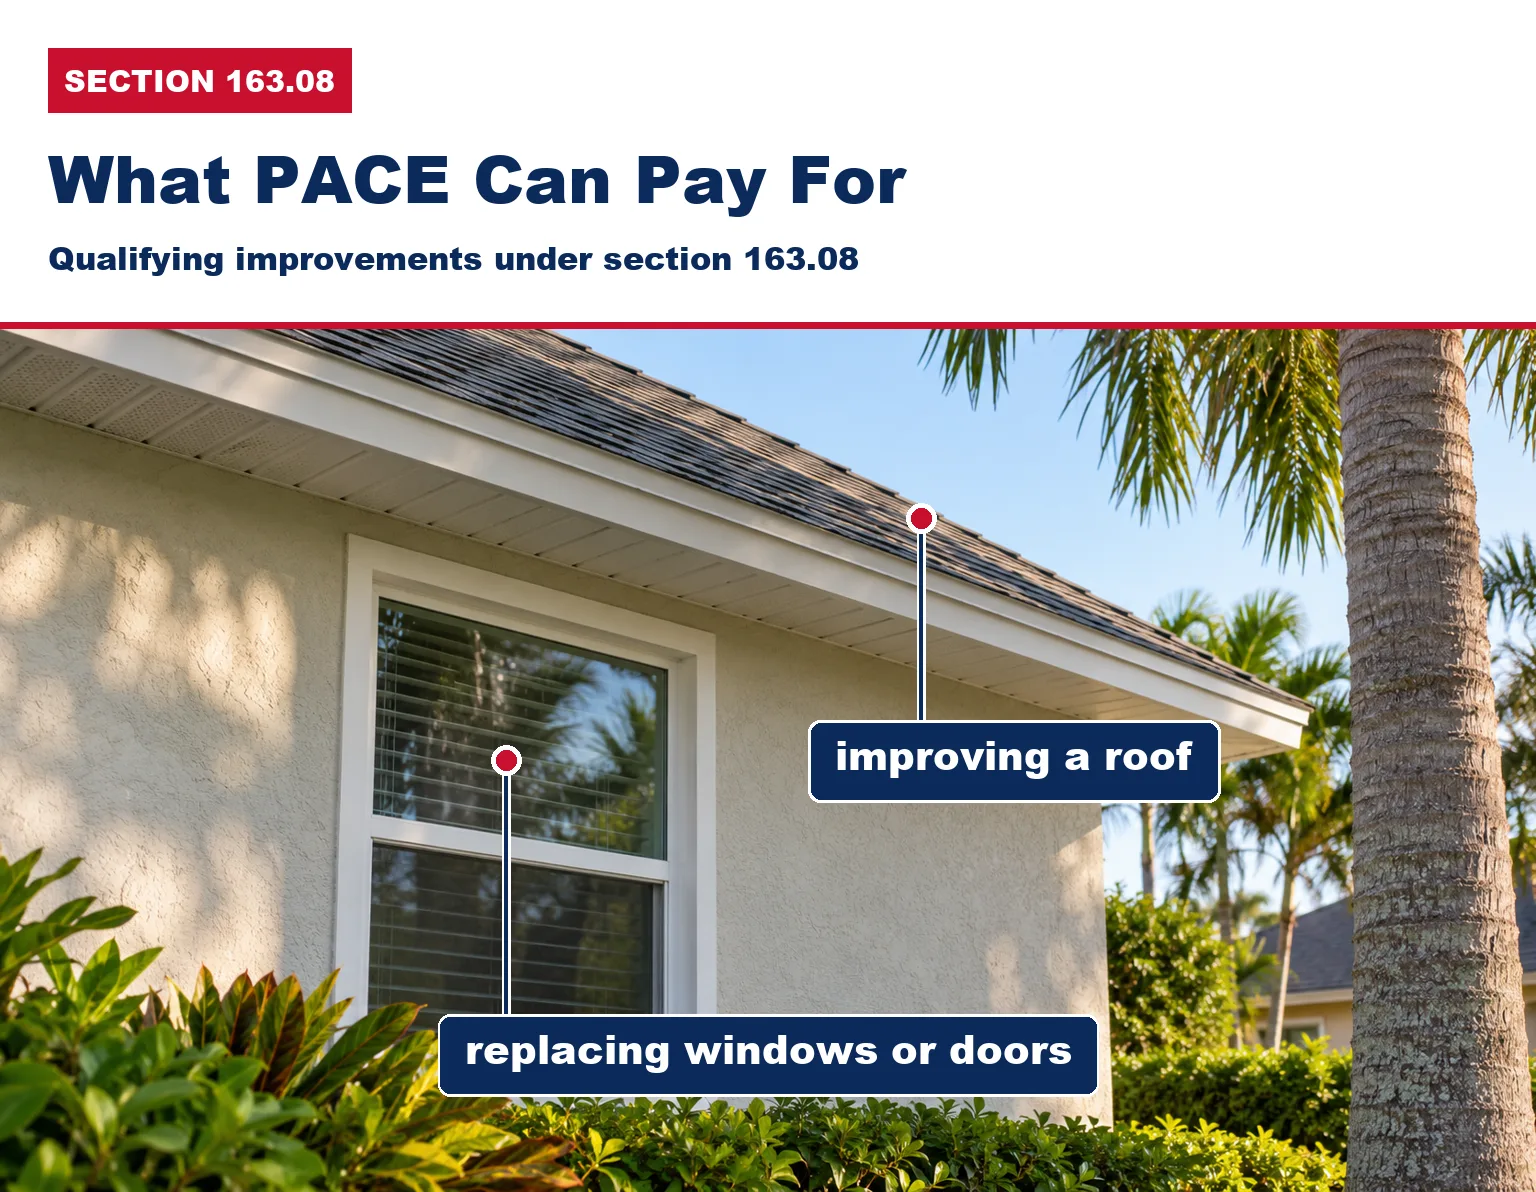
PACE money can only pay for the qualifying improvements listed in section 163.08, Florida Statutes. For homes, the list includes replacing windows or doors, including garage doors, with impact-resistant ones, installing storm shutters, and improving a roof with wind-resistant shingles or roof-to-wall reinforcement.
It also covers insulation, energy-efficient cooling systems, permanent generators and solar.
A home equity loan or HELOC is not tied to that list, so the same loan could cover new impact windows and a kitchen remodel. See which Florida projects qualify for PACE funding for the full breakdown, or compare the impact window styles USA Home Improvement installs.
Consumer Protections: PACE Rules vs Home Equity Lending Rules
All three options come with a cancellation window and required disclosures, but Florida PACE adds two extra steps: a recorded confirmation call and a written notice to your mortgage holder at least 5 business days before you sign.
The federal PACE rule also gives PACE its own Loan Estimate and Closing Disclosure forms, as for other home loans.
For a home equity loan, the federal right of rescission gives you three business days to cancel. In this case, business days include Saturdays but not Sundays or legal public holidays.
For a HELOC, you can cancel in writing within the first three days after the account opens, and the lender must return the fees you paid. HELOC lenders must also disclose the APR, variable-rate terms, payment terms and fees.
One HELOC risk has no PACE match: the lender can generally freeze or reduce your line if your home’s value falls.
Selling or Refinancing With PACE vs a Home Equity Loan
A home equity loan or HELOC is normally paid off when you sell. The CFPB says you are generally required to pay off a HELOC in full immediately when you sell, and repayment of a home equity loan is often required at sale too.
PACE looks different on paper because the assessment stays with the property’s tax bill. Florida’s required disclosure still warns that if you sell or refinance, a mortgage lender may require you to pay off the full amount owed.
Federal mortgage rules explain why. Under FHA Mortgagee Letter 2017-18, properties with PACE obligations are no longer eligible for FHA-insured forward mortgages, though a rate-and-term or cash-out refinance may pay the PACE balance off.
Fannie Mae’s Selling Guide says it will not buy mortgages on homes with an outstanding PACE loan, unless the PACE program gives no lien priority over first mortgages.
The FHFA’s statement on PACE liens adds that buyers of a home with a first-lien PACE loan cannot use a Fannie Mae or Freddie Mac loan for the purchase.
If your buyer plans to use one of those loans, expect the PACE balance to be paid off at closing. For refinance options and the payoff steps, read refinancing a mortgage with a PACE assessment.
Which Option Fits Your Florida Home Project
The right choice depends on your project, your equity and how long you plan to stay. Use these conditions as a starting point, then compare written offers:
- PACE may fit when your project is on the qualifying list, you meet the tax, mortgage and income tests, you can budget for a higher tax bill, and you do not expect to sell or refinance soon.
- A home equity loan may fit when you know the full project cost up front, have equity in the home, and want one fixed payment.
- A HELOC may fit when costs will come in stages and you are comfortable with a payment that can change.
Whatever you choose, compare the APR, total cost and term in writing before you sign. HELOC lenders must give you a list of HUD-approved housing counselors, who offer free or low-cost help reviewing how a loan fits your budget.
PACE and Home Equity Loan FAQs
Is PACE a loan or a tax?
PACE is both, depending on the rule you read. Florida levies it as a non-ad valorem assessment collected with your property taxes. The CFPB’s federal rule treats residential PACE as credit under the Truth in Lending Act, so lending disclosures and repayment checks apply.
Does a PACE lien come before my mortgage?
A Florida PACE lien ranks with property taxes. Section 163.081 makes the recorded assessment a lien “of equal dignity to county taxes and assessments.” That is why Fannie Mae will not buy mortgages on homes with an outstanding PACE loan that has lien priority over first mortgages.
Can I get PACE if I have a reverse mortgage?
No. Florida law does not allow a residential PACE agreement on a property that already has a home equity conversion mortgage or another reverse mortgage product.
Are PACE payments tax deductible?
It depends on how the assessment and your project are treated for your return. Read whether PACE payments are tax deductible, and ask a tax professional about your own situation before you file.
Price the Project Before You Pick the Financing
A firm project price makes every financing offer easier to compare. USA Home Improvement exclusively sells ES Windows impact windows and doors, every project is permitted, and you can receive the Florida Product Approval number for each window and door on request.
USA Home Improvement is licensed (CGC1526707) and insured and has served Florida homeowners for more than 15 years.
Get a free estimate or call (877) 554-6373.